Mike Kaye, co-founder and director, Sarah Kaye & Co. Buyers Agents
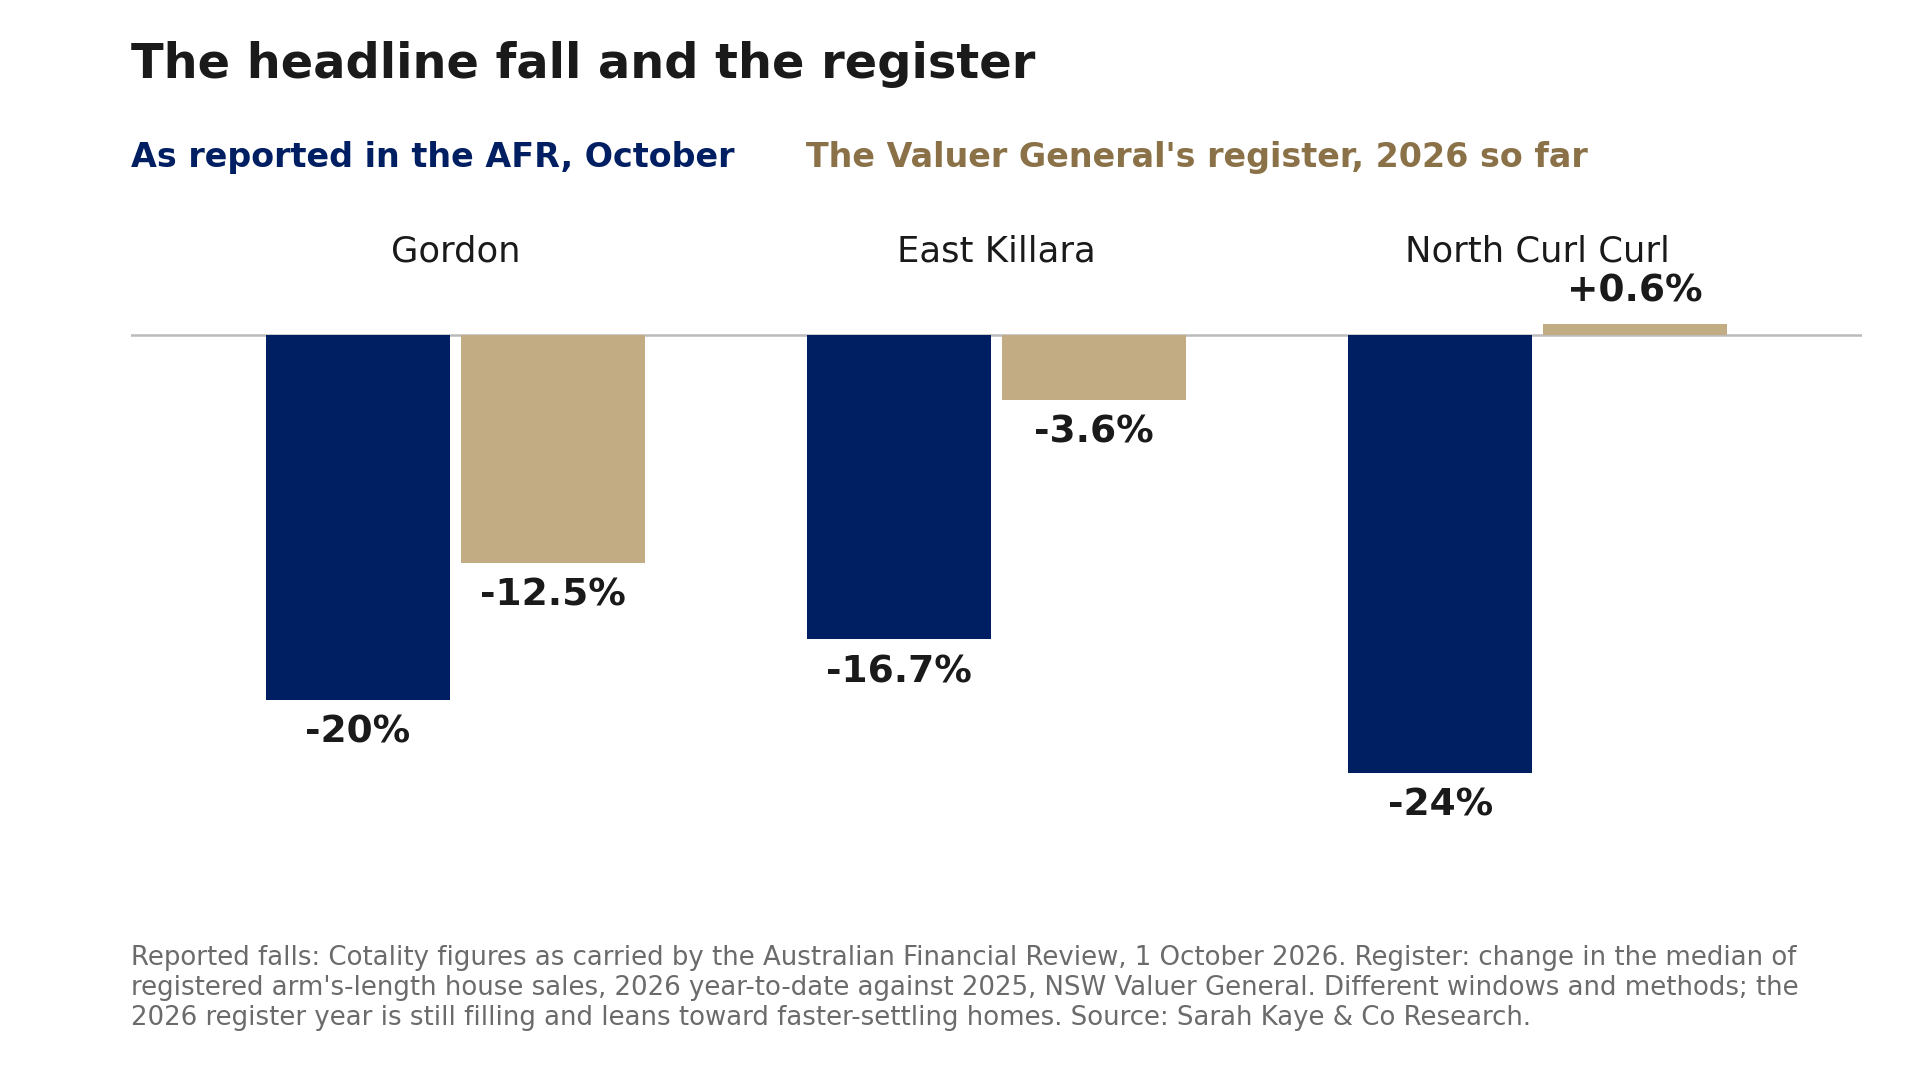
In early October, the Financial Review put our neighbourhood on the front page. Gordon, down 20%. East Killara, down 16.7%. And across at
North Curl Curl, the steepest fall in the nation: 24%. Uncomfortable reading over breakfast if you own in any of them.
Regular readers had already met the Gordon number. Gordon is off 19% on Cotality’s reading, as we wrote last month. So we are not going to tell you the papers have it wrong. Sales volumes are weak, clearance is poor, and the register confirms both. But a suburb median is a blunt instrument, and this is the month to show what it measures and what it doesn’t.
What a thin median measures
A median is the middle price of whatever happened to sell. In a big market, that is useful. In our suburbs, it is noisy. North Curl Curl trades about 40 houses in a normal year. Which handful sells moves the number more than prices do.
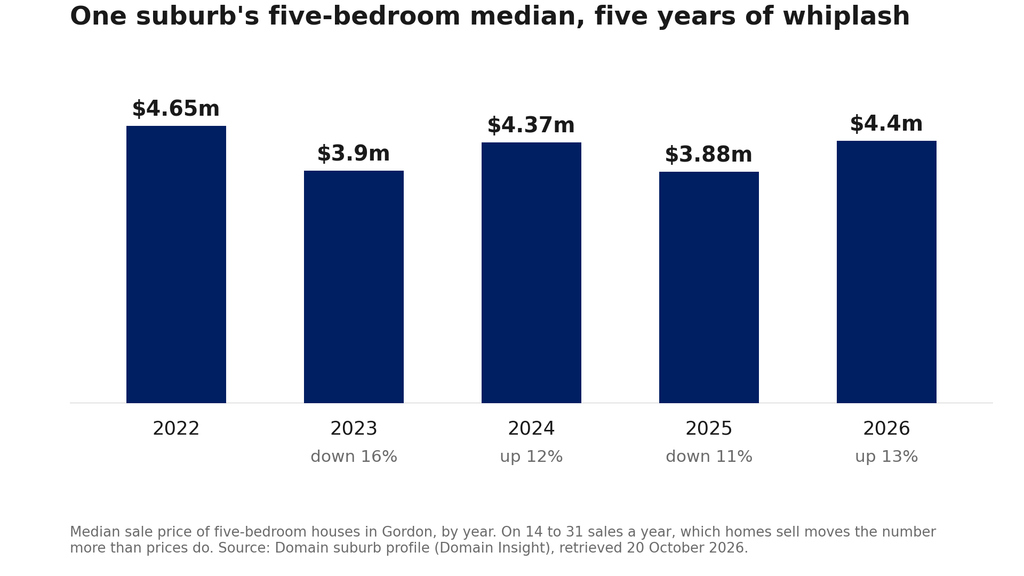
Gordon illustrates the point. Domain’s median for a five-bedroom house in Gordon: down 16% in 2023, up 12% in 2024, down 11% in 2025, up 13% this year. Five years of boom and bust in one chart. Nobody’s home did any of that. The mix of sold homes did.
Now put the front page beside the Valuer General’s register. North Curl Curl’s registered house sales this year show a median of $3.9 million, against $3.88 million last year and $3.8 million the year prior.
Flat. East Killara: $3.58 million against $3.72 million, down about 4%. Gordon is genuinely softer, off about 12% on the same measure. The fall is real, but its size depends on the ruler. (One caveat – and it runs in one direction: this year’s register is still filling and, as dear homes settle slowest, these medians will drift up as the year completes, not down.)
We can make a scary number too
From the same register: of this spring’s sales already settled in our 10 suburbs, 11 of the 13 houses were under $2.5 million, so the early house median is
$1.95 million. Down 42% on last spring, if you wanted a (Halloween) headline. The same early read in 2024 was also exactly $1.95 million, in a spring that finished perfectly well.
Cheap homes settle fast and dear homes slowly, so an early median measures settlement speed, not value. We’ll quote spring’s medians when they settle.
Spring against the bar
Last month we set spring’s test before the season could influence it: winter’s resellers typically made 2.5% on the home they sold, and a third took a loss. Beat that and the season worked.
The first spring resales have now reached the register. Four clean pairs, which is as thin as evidence gets: a typical gain of about 6%, one of the four at a loss, and mostly apartments, the quick settlers. A straw in the wind, leaning the right way. December gives the verdict.
The five-bedroom tale
October’s open question: does the school-year clock bring family buyers back to the big houses? We promised the five-bedroom tale either way. The season still has six weeks to run at our deadline, so here is half-time.
Across nine of our 10 suburbs, five-bedroom clearance averages 44% over the trailing year, exactly where it stood when we set the question. Killara and Gordon have edged up from a third to 36% and 39%. Roseville is the outlier at 59%. No rush of family buyers yet. No collapse either.
As Upper North Shore buyers’ agents, we spend most Saturdays at open homes, and the front doors agree. This is a field note, not a statistic. Under
$2 million, noticeably more buyers at the first opens of fresh, well-kept homes. Between $2 million and $5 million it is patchy, but the genuinely good homes draw a crowd in their first fortnight. Over $5 million, quiet: some suburbs have little to buy, others have the stock but no takers.
Between the forecasts
HSBC says the downturn is not even halfway done and expects a 13% fall overall. The Housing Industry Association’s economist expects prices to stabilise late this year, with buyers returning in early 2027. And Stockland reports its downsizer customers delayed because they cannot sell the family home, which is the squeeze we described in September, seen from the seller’s side.
The early evidence sits closer to stabilising. Resellers back to modest gains, buyers returning at the entry end first, and a cash rate at 4.6% with November’s meeting falling mid-season.
Watch two things this month:
Whether the crowds at the entry-level opens turn into exchanges and the full spring resale read.
The front page told you what happened to three medians – in Gordon, East Killara and North Curl Curl. The register will tell you what happened to the homes.